

Budget App — PocketGuard
PocketGuard, Inc.
- 4.5
- 1.17K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
Budget App — PocketGuard Pros and Cons
Pros
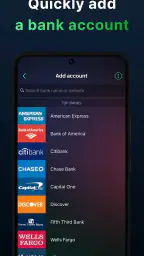
- Links bank accounts and cards for an up-to-date financial overview.
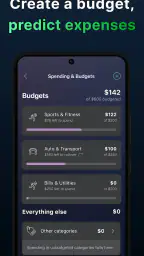
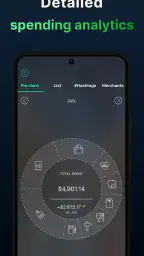
- Spending categories make it easier to identify where your money goes.
- Bill tracking can help prevent missed recurring payments.
- Savings goals add structure to short- and long-term financial planning.
- Clean interface makes essential budget information quick to scan.
Cons
- Many useful features require a paid PocketGuard subscription.
- Bank connection availability may vary by country and financial institution.
- Automatic transaction categorization can occasionally need manual corrections.
- Some users may be uncomfortable sharing financial account access.
- Limited customization may frustrate people wanting highly detailed budgets.
 Analysis by All-app
I have always found budgeting apps most useful when they reduce the distance between earning money and understanding where it goes. PocketGuard takes that practical route. It is a finance app from PocketGuard, Inc. designed for tracking spending, organizing income, controlling expenses, and helping users save. After spending time with it, my impression is that it works best as a day-to-day money overview rather than as a complete replacement for a spreadsheet, a banking app, or a detailed financial planning tool.
The appeal is easy to understand: instead of asking you to build a complicated budget from scratch, it aims to turn your financial activity into something easier to read. That makes it approachable for someone who wants more control but does not enjoy working with tables and categories manually. At the same time, the convenience comes with trade-offs. Anyone who expects deep customization, highly detailed forecasting, or total control over every budgeting rule may find the experience less satisfying.
How PocketGuard fits into everyday money management
PocketGuard belongs in the personal finance category, but its role is narrower and more focused than that label might suggest. I see it as a companion for people who need a clearer picture of routine spending. It can help you look at income, expenses, and saving goals in one place, then use that overview to make better decisions before the next purchase.
That distinction matters. A traditional spreadsheet gives you complete freedom, but you must decide how to structure it, enter information, maintain formulas, and remember to update everything. A bank application is excellent for checking balances and transactions, yet it may not explain how your spending fits into a monthly plan. PocketGuard sits between those two approaches. It tries to make financial awareness more immediate without requiring the user to become a spreadsheet expert.
I would not describe it as a magic solution for overspending. The app can organize information and make patterns easier to notice, but the useful decision still belongs to you. Its real contribution is reducing the effort needed to ask sensible questions: How much have I already spent? Which expenses are taking more room than expected? Can I afford this purchase without making the rest of the month uncomfortable?
Cost, access, and what “free” really means here
PocketGuard is free to download, which makes it easy to try before deciding whether it deserves a permanent place on your phone. The app is suitable for Everyone, so its presentation is not aimed at a specialist financial audience. The free entry point is valuable for curious users who want to test the basic experience without committing money immediately.
There are also in-app purchases, with individual items ranging from less than a dollar to well over a hundred dollars. That wide range is important when judging value. “Free” means you can begin without paying for the download, but it does not mean every possible capability is included at no cost. I would check the purchase screen carefully before upgrading and think about which functions I would actually use rather than assuming that a paid option automatically improves my finances.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
For me, the sensible approach is to start with the free access, establish a real weekly routine, and only then consider spending money inside the app. If I am not opening a budgeting tool often enough to change a decision, paying for additional access is unlikely to solve the underlying problem. The value of a finance app comes from consistent use, not simply from unlocking more settings.
What you can realistically get from the experience
The strongest value is the reduction of mental clutter. When income and expenses are viewed together, ordinary purchases become easier to judge in context. A coffee, a subscription, or an unplanned online order may seem harmless in isolation. Seeing several of those choices within the same spending picture can make the monthly effect more obvious.
I also like the idea of using the app as a short review ritual rather than constantly watching every transaction. A quick check at the start of the week can show whether the previous few days were unusually expensive. Another check before a large purchase can prevent the common mistake of judging affordability only by the current account balance.
The most useful habit is to treat the app as a decision checkpoint, not as a financial scoreboard. If I open it only to feel guilty about spending, it becomes discouraging. If I use it to decide what can change before the month gets away from me, it becomes practical.
A realistic monthly scenario
Imagine that I receive my regular income near the beginning of the month. Rent and other fixed commitments leave my account quickly, while groceries, transport, meals out, and small digital purchases continue throughout the weeks. Without a separate overview, I might look at the remaining balance and assume I have plenty of room. PocketGuard can make the difference between the current balance and genuinely available money easier to think about.
In that situation, I would review the app after the first week instead of waiting until the balance looked worrying. If dining out had already taken a large share of the flexible spending, I could choose cheaper meals for the next few days and protect money needed for groceries. The app would not make that choice for me, but it could make the timing of the choice much better.
A second useful routine would be checking before a nonessential purchase. Rather than asking, “Is there enough money in my account today?” I would ask, “Will this purchase still fit after the expenses I know are coming?” That change in wording is small, but it is one of the more valuable lessons a budgeting tool can encourage.
Three practical ways to use it beyond the basic overview
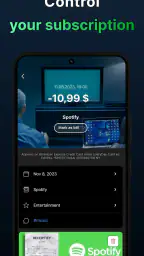
First, I would use PocketGuard as a subscription-awareness tool. Recurring charges are easy to ignore because they are often small and automatic. A weekly review can reveal services that no longer justify their place in the budget. The important step is not merely noticing them; it is deciding whether each one still supports a real habit or goal.
Second, I would separate “unexpected” expenses from genuinely irregular expenses. A car repair, annual bill, or seasonal purchase may feel surprising when it arrives, but it is not necessarily unpredictable over a longer period. When reviewing spending, I would mark these events mentally and create a small buffer for them in future months. That turns the app from a record of past problems into a prompt for better preparation.
Third, I would use it during a short spending reset rather than attempting an extreme permanent budget. For one or two weeks, I could review purchases more deliberately, identify the categories that cause the most leakage, and then keep only the changes that feel sustainable. This is more realistic than cutting every enjoyable expense and abandoning the plan after a few days.
Where the convenience can become frustrating
The same simplicity that makes PocketGuard approachable may feel restrictive to people who want to design every part of their financial system. A user with several income sources, complex reimbursements, shared household finances, or detailed business expenses may need more control than a streamlined budgeting app is intended to provide.
There is also a difference between seeing a spending pattern and understanding why it happened. A category can tell me that money went somewhere, but it may not explain whether the expense was necessary, emotional, poorly planned, or simply part of an unusual week. I still need to add judgment and context. No app can replace an honest review of habits.
Another limitation is behavioral rather than technical: the app only helps when I give its information attention. Someone who dislikes reviewing finances may download it enthusiastically and then stop opening it. In that case, a simple calendar reminder and a basic note might be more useful than a feature-rich budgeting tool that is ignored.
How it compares with familiar alternatives
Compared with a spreadsheet, PocketGuard is more convenient for users who want a ready-made financial view and do not want to build formulas or maintain a personal system. A spreadsheet wins when I need unusual categories, custom calculations, long-term projections, or a record designed exactly around my household. It also gives me more visibility into how every figure was produced, provided I maintain it carefully.
Compared with a bank app, PocketGuard is more focused on budgeting behavior than on basic account access. A bank application is usually the place I go to move money, confirm a payment, or inspect a particular transaction. PocketGuard is more useful when I want to step back and consider the relationship between income, spending, expenses, and saving.
Compared with a notebook or envelope-style cash system, it offers less physical friction. That can be an advantage because I do not need to carry separate notes or update a paper ledger. However, physical systems can feel more tangible and may work better for someone who responds strongly to visible limits. The best choice depends on whether convenience or deliberate manual involvement helps that person stay consistent.
Who is likely to get the most value?
I think PocketGuard is a good match for someone who has regular income, wants a clearer view of everyday spending, and needs encouragement to check finances before making purchases. It is especially suitable for a beginner who finds full budgeting systems intimidating. The free starting point lowers the risk of trying it, while the focus on spending and expenses keeps the first steps understandable.
It may also help people who earn enough to cover their needs but still wonder where their money disappears. That situation is common: the problem is not always low income, but a lack of visibility across many small decisions. A straightforward overview can reveal the pattern without requiring a complete lifestyle overhaul.
I would be more cautious about recommending it as the main tool for couples who need detailed shared planning, freelancers with irregular business income, or users who want investment analysis and advanced forecasting. Those needs call for a more specialized system, possibly alongside a budgeting app rather than inside one. PocketGuard can still provide a useful spending snapshot, but it should not be forced to serve as an accounting platform.
Device expectations and long-term upkeep
The app runs on Android devices using version 8.0 or later. That makes checking compatibility worthwhile before installing, particularly if the phone is older. PocketGuard has been available since March 16, 2016, and the current version is 5.19.3, so it is not a brand-new experiment. The developer is PocketGuard, Inc., and the app has passed the early stage where a product is still trying to prove that it has a lasting purpose.
Its audience is also visible in its store presence: it has more than two thousand ratings, an average rating of 4.5, and over a hundred thousand installs. Those figures suggest that many people have found the concept approachable, although popularity alone does not tell me whether it fits my particular financial habits. I would still judge it by how quickly it helps me make a better decision during an ordinary week.
Long-term success will depend on maintenance. I would set a recurring weekly review, keep the session short, and avoid turning every purchase into a moral judgment. If the app makes me more aware without making budgeting exhausting, it is doing its job. If it creates more confusion than clarity, I would simplify the system or switch to a method I can actually sustain.
My final recommendation
My recommendation is positive, with a clear condition: try PocketGuard if you want a friendly way to understand spending and control everyday expenses, but do not expect it to replace detailed financial planning. Its free access makes experimentation sensible, while the in-app purchase range means I would delay any paid decision until I had proved that the app had become part of my routine.
I would choose it over a spreadsheet when speed and accessibility matter more than total customization. I would choose a spreadsheet or a more specialized finance tool when my situation involves complicated income, shared accounting, or detailed forecasting. For a person who simply wants to stop guessing whether there is enough money left for the rest of the month, PocketGuard offers a useful starting point.
In my experience, its best result is not a perfectly optimized budget. It is the moment when a purchase becomes a conscious choice instead of an automatic one. If that is the change you are looking for, PocketGuard is worth trying. If you already enjoy building detailed financial systems and need complete control over every rule, I would skip the upgrade path and use a more flexible alternative instead.
Frequently Asked Questions
What is PocketGuard, and how does it help with budgeting?
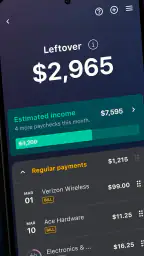
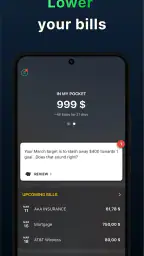
PocketGuard is a personal finance and budgeting app designed to give you a clearer view of your money. After connecting eligible financial accounts, it organizes balances, income, bills, and spending in one place. Its main feature, often presented as “In My Pocket,” estimates how much money may remain available after recurring bills, savings goals, and everyday expenses are considered.
Is PocketGuard safe to use with my bank accounts?
PocketGuard uses account-connection services and security measures intended to protect the financial information you provide. However, users should still review the app’s privacy policy, supported connection provider, permissions, and data-sharing practices before linking accounts. You should also enable device security, use a strong password, and avoid accessing sensitive financial information on unsecured public Wi-Fi networks.
Does PocketGuard automatically track spending and categorize transactions?
Yes, PocketGuard can automatically import transactions from connected financial accounts and organize them into spending categories. In testing this type of feature, categorization is useful for quickly identifying habits, although some transactions may be assigned incorrectly or require manual adjustments. Regularly reviewing categories and merchant names helps keep reports, budgets, and available-money estimates more accurate.
Is PocketGuard free, or does it require a subscription?
PocketGuard may offer free budgeting features, but access to advanced tools can depend on the current plan, platform, region, or promotional offer. Premium features may include enhanced budgeting controls, customized categories, debt-related tools, or additional financial insights. Before downloading or subscribing, check the latest pricing shown in the App Store or Google Play and review renewal terms carefully.
Who would benefit most from downloading PocketGuard?
PocketGuard is best suited to people who want a straightforward overview of income, bills, spending, and the money potentially available for daily use. It can be especially helpful for beginners who prefer automation instead of building a detailed spreadsheet. Users seeking advanced investment analysis, complex household budgeting, or complete manual control may find that the app’s approach is less flexible.


